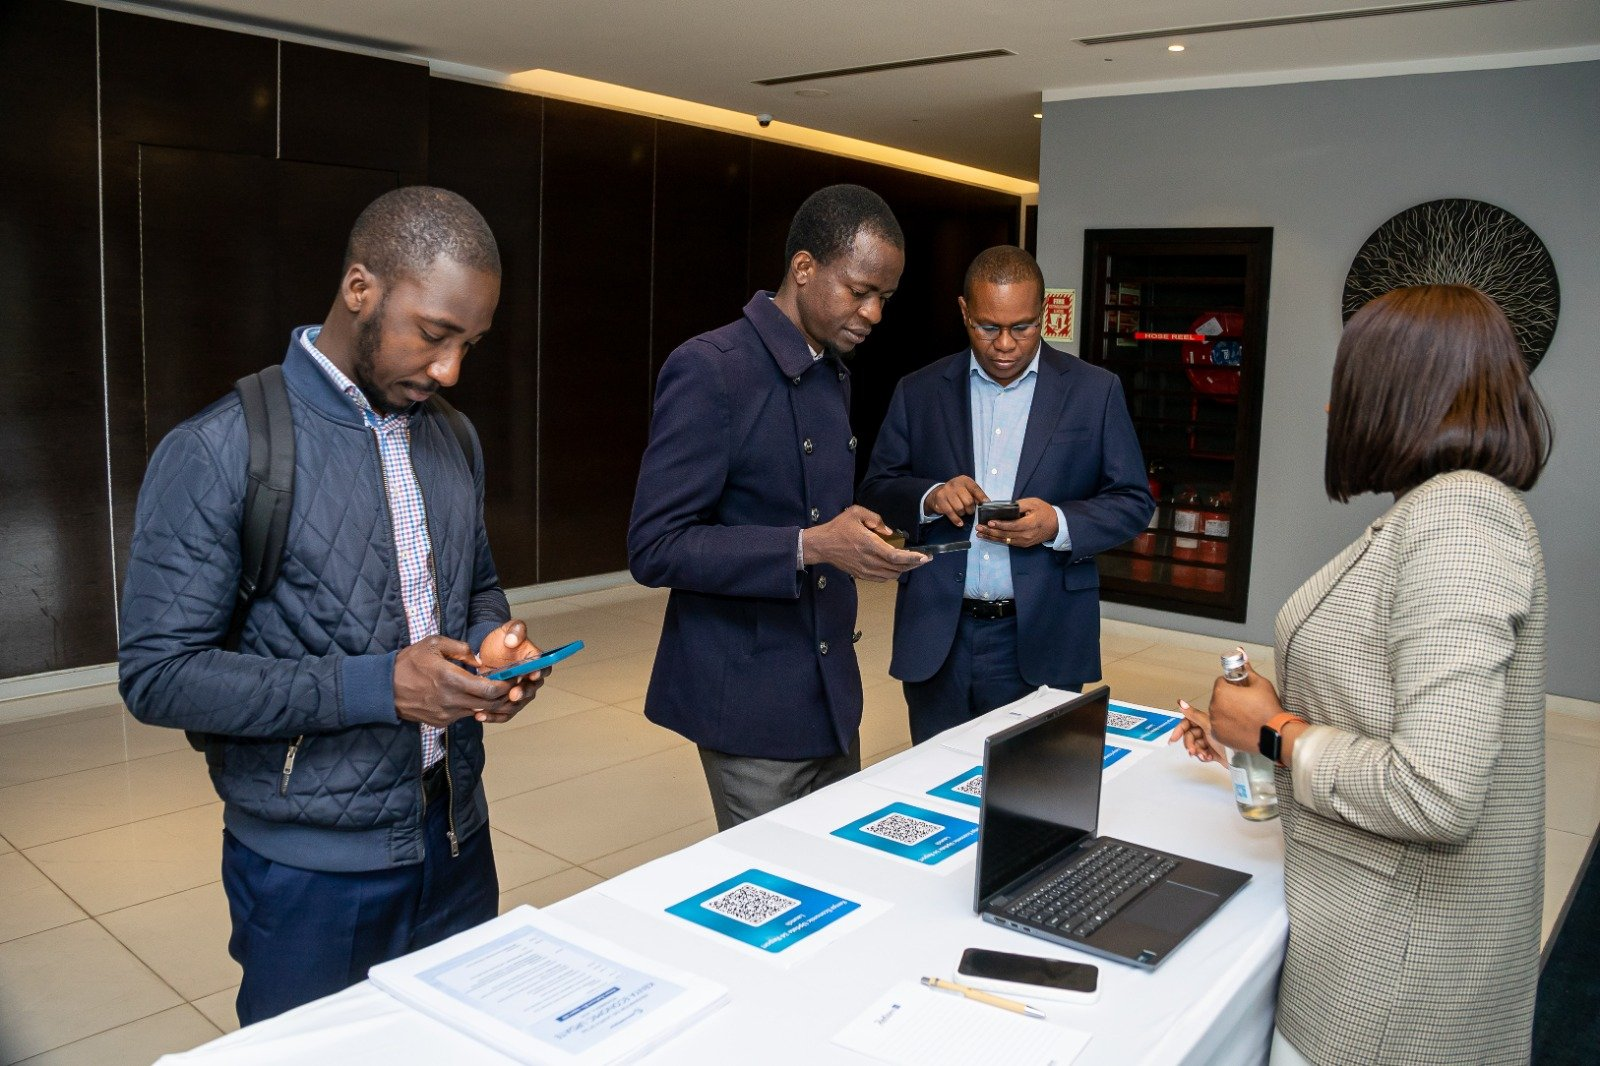
In the bustling streets of Nairobi, the coastal towns of Mombasa, and the rural heartlands of Kenya, a quiet but powerful economic undercurrent is reshaping daily life. Millions of Kenyans are reaching for their phones not just to chat or transfer money, but to borrow, often in small amounts, for short periods, to cover the basics. Reports published this week paint a vivid picture of a nation leaning heavily on credit, particularly the fast, accessible kind offered by digital lenders.
According to data from the Central Bank of Kenya (CBK) highlighted in coverage this week, the outstanding loan book of licensed digital credit providers (DCPs) climbed to Sh153.8 billion by the end of June 2026. That represents a sharp 39.6 percent jump in just six months from Sh110.1 billion in December 2025. Over a full year, the book has roughly doubled from about Sh76.8 billion in June 2025. Businessdailyafrica
The number of loan accounts tells an even more striking story of scale: rising from 6.74 million in December 2025 to 8.9 million by June 2026. Most of these loans are modest, typically under Sh20,000, with terms ranging from one week to two months. They serve as emergency buffers or quick working capital, but the CBK has cautioned that their small size often limits their ability to fund investments that could meaningfully raise household or business incomes. Riotimesonline
Complementing the CBK figures, industry voices reported this week that Kenyans are accessing more than Sh13 billion in digital loans every month. Kevin Mutiso, Chair of the Digital Financial Services Association of Kenya (DFSAK), noted that around 5.5 million Kenyans currently tap these facilities from dozens of registered providers. Accounts in the broader digital space have grown dramatically over recent years, from hundreds of thousands to millions, as people seek to offset basic needs amid uneven economic conditions. Kenyanews
“While most borrowers take out loans primarily for consumption, [the sector] has also supported Kenyans in financing their enterprises and start-ups,” Mutiso observed. He pointed to practical impacts, including financing for smartphones and support for livelihood assets.
Yet the boom carries clear risks. Sam Omukoko, Founder and Group Managing Director of Metropol Credit Bureau, flagged rising non-performing loans in the digital sector, averaging around 20 percent. He linked the trend to harsh economic pressures and the prevalence of borrowing for day-to-day consumption rather than productive investment or growth. Metropol has registered data on tens of millions of credit accounts, underscoring how widespread formal and semi-formal borrowing has become. Kenyanews
The growth in digital credit sits alongside a more mixed picture in traditional banking. Commercial bank average lending rates have eased to around 14.4 percent (as of mid-to-late 2026 data referenced this week), down from higher levels in prior years, with some banks offering rates as low as about 12 percent. Trade Cabinet Secretary Lee Kinyanjui highlighted the improvement, attributing part of it to better fiscal management and rising deposits. “Just about two, three years ago… the average interest rate… was in the range of 18, 19, and so on. But through prudent fiscal management, that number has come down and there are banks that are actually lending at about 12 percent,” he said. Businesstoday
Treasury Cabinet Secretary John Mbadi, however, struck a more impatient note this week, arguing that credit remains costly for many and urging banks to pass on more of the benefits from the Central Bank Rate, which has been held at 8.75 percent. Private-sector credit growth has shown signs of recovery, but high non-performing loans in the broader banking system (with absolute volumes still elevated even as ratios improve) and the government’s own borrowing needs continue to influence the cost and availability of formal credit. Kenyanwallstreet
In some counties, the high cost of bank loans has visibly cooled demand. In Kiambu, for instance, one KCB branch officer reported a sharp drop in loan applications and amounts as rates moved into the low-20s range for some products, illustrating how interest rates still shape borrowing behavior. Kenyanews
Snapshot of the Digital Lending Surge (key figures from reports this week)
| Indicator | Figure | Period / Note |
|---|---|---|
| Outstanding digital loans | Sh153.8 billion | June 2026 |
| Growth from Dec 2025 | +39.6% (from Sh110.1 bn) | 6 months |
| Year-on-year roughly | Doubled (from ~Sh76.8 bn) | June 2025–June 2026 |
| Loan accounts | 8.9 million | June 2026 (from 6.74 m Dec 2025) |
| Monthly digital borrowing | Over Sh13 billion | Recent industry estimate |
| Approximate users/reach | ~5.5 million Kenyans | Industry association data |
| Licensed DCPs | 281 | By around Sept 2026 |
| Digital sector NPLs (approx.) | ~20% | Industry comment |
The surge reflects both opportunity and pressure. Digital platforms have democratised access to credit for millions who might previously have relied on informal networks, family, or high-cost alternatives. At the same time, the heavy tilt toward short-term, consumption-focused borrowing—combined with still-elevated formal interest rates and economic headwinds such as inflation around 7.3 percent—raises questions about household resilience and long-term financial health.
Regulators are responding. New rules are tightening oversight of digital lenders, including requirements around the use of artificial intelligence in credit decisions, greater transparency, and stronger consumer protections. Industry players are also pushing for higher capital thresholds to weed out weaker or unscrupulous operators.
For now, the data is clear: Kenyans are borrowing at a high rate, especially through their phones. Whether this wave of credit eases short-term pressures or deepens longer-term vulnerabilities will depend on how quickly the economy generates more sustainable incomes, how effectively rates continue to moderate, and how well borrowers and lenders navigate the thin line between useful liquidity and unsustainable debt. The reports this week offer a timely window into a defining feature of Kenya’s current economic moment.